September 2026 Developers’ Sales: New Home Sales Rebound from Low Base as Buyers Revisit Earlier Launches
Research15 Oct 20266 min read

In September 2026, developers sold a total of 296 private homes (excluding ECs). Amid August’s low base of just 153 units sold, this represents a 93.5% month-on-month (m-o-m) increase in the number of private homes sold on the primary market. However, this figure is 86.2% lower than the 2,142 units moved in the same month last year.
New private home supply also rose 36.2% m-o-m from August’s 116 units to 158 units launched in September. This includes 70 units launched at Amberwood At Holland, out of a total of 212 units in the entire project.
Within the Executive Condominium (EC) segment, developers sold 23 new units, reflecting a 27.8% m-o-m increase from the 18 units shifted in August. Compared to the 15 EC units sold in September 2025, this represents a 53.3% uptick on the year.
Table 1: New home sales over the last six months (excluding ECs)
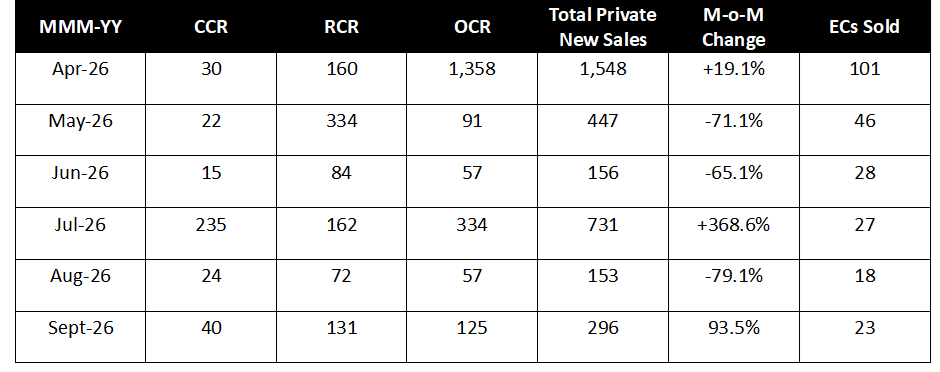
Table 2: Top performing new non-landed projects in September 2026 (excluding ECs)
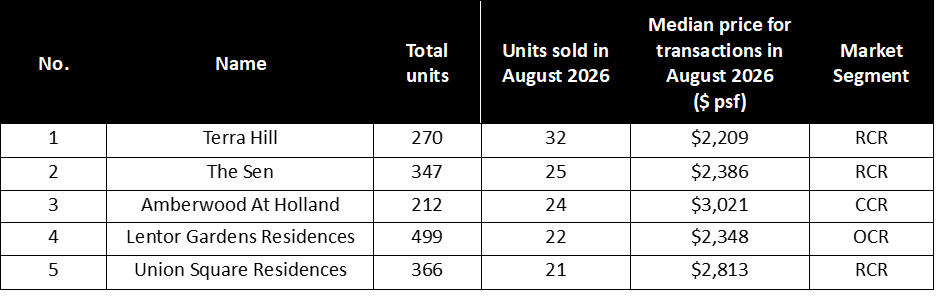
Terra Hill and The Sen See Sharp Pickup in Sales as Attractive Pricing and Launch Activity Renew Buyer Interest
Both Terra Hill and The Sen emerged as September’s top selling projects, moving 32 and 25 units respectively. This was a noticeable pickup from August, when the two projects sold just four and 12 units.
Attractive pricing may have been a key factor behind the rebound in sales. At $2,209 psf for Terra Hill and $2,386 psf for The Sen, September’s median new sale prices for both projects sat below the wider RCR equivalent of $2,522 psf for new non-landed private homes. These price points had likely appealed to value-conscious buyers seeking accessible entry into the city fringe before growing RCR land costs filter through to future launches.
Additionally, Amberwood At Holland’s debut may have turned the spotlight on the area, given that The Sen also sits within the Bukit Timah planning area, while Terra Hill is located in adjoining Queenstown.
Amberwood At Holland Sees Measured Launch Response, Uptick in Sales Possible in Coming Months
As September’s sole new launch, Amberwood At Holland saw measured sales, moving 24 units across the month. Although the project has 212 units in total, only 70 were released for sale during its initial launch weekend.
However, sales could pick up as buyers recognise the project’s first-mover advantage amid the ongoing development of the Holland Plain precinct. With Methodist Girls’ School within 1 km, as well as Pei Hwa Presbyterian Primary School and Henry Park Primary School within 2 km, this could also eventually appeal to more families.
Fewer Homes Sold Below $2.5M in September as Sales of Larger Units Gain Traction
In September, fewer new non-landed private homes (excluding ECs) were sold below the $2.5 million mark. Based on URA caveat data (as at 15 October 2026), transactions below $2.5 million accounted for around 38.8 % of total monthly sales, down from 60.3% in August.
This decline corresponded with a higher concentration of sales in the $2.5 million to $3 million quantum range, which accounted for a 23.1% share.
Stronger take-up for larger 3- and 4-bedroom units at existing developments such as Lentor Mansion and Terra Hill helped drive the higher transaction share in this bracket. This was also supported by Amberwood At Holland, where unit offerings consist exclusively of three-bedroom and larger layouts.
New EC Sales Remain Soft as Buyers Await Fresh Options
In September, developers sold 23 new ECs, representing a 27.8% m-o-m uptick from the low base of 23 units sold in August.
Coastal Cabana continued to lead new EC transactions for the fourth consecutive month with 19 units sold at a median price of $1,811 psf. Rivelle Tampines, which launched in March, accounted for two of the remaining new EC units sold, while Altura and Otto Place recorded one transaction each.
Chart 1: Number of unsold EC units and EC units sold
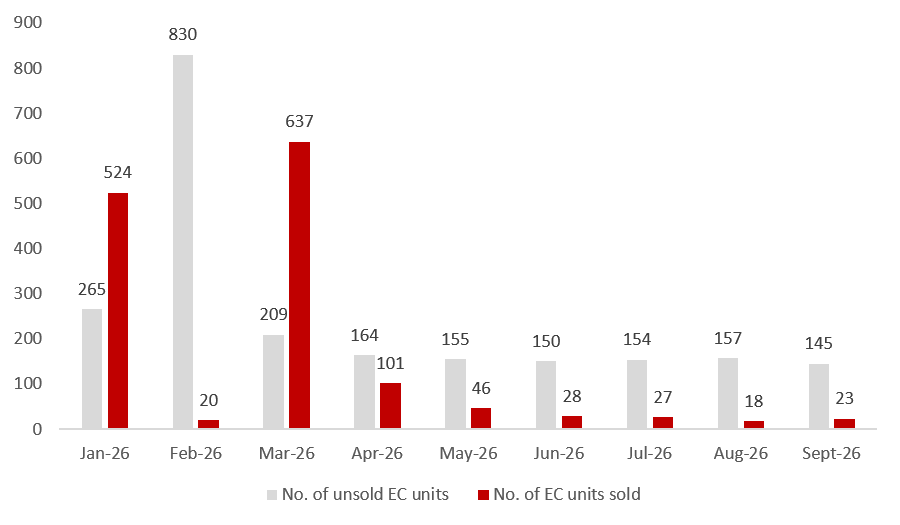
Based on developers’ sales records, only 145 EC units remain unsold as of end-September. This tight inventory is likely to keep new EC sales muted until future launches reignite buyer interest with fresh options in both layouts and locations.
Wynwood Grand, the next EC project to launch, is slated for a 4Q 2026 preview. It could draw strong interest from HDB upgraders and first-time buyers as the first EC development in the Woodlands planning area in more than a decade. The project will comprise 420 units and is among the last projects to come under the previous EC rules, including a five-year Minimum Occupation Period and access to the Deferred Payment Scheme.
Buyer Profile
Chart 2: Buyer profile for all new non-landed private homes (excluding ECs)
Singaporean Citizens continued to dominate new non-landed private home purchases in September, making up 85.4% of transactions, or 229 units, according to URA caveat data as at 15 October 2026. Permanent Residents accounted for 33 units, or 12.3% of transactions.
The 60% Additional Buyer’s Stamp Duty (ABSD) continued to dampen foreigner demand. Only six foreign purchase was recorded in September,[EC1] representing 2.2% of total transactions. Although foreign participation remained minimal, Singapore’s stable and transparent real estate market should continue to attract overseas buyer interest over the longer term.
Luxury Homes
Chart 3: Buyer profile for non-landed private homes (excluding ECs) transacted at $5mil and more
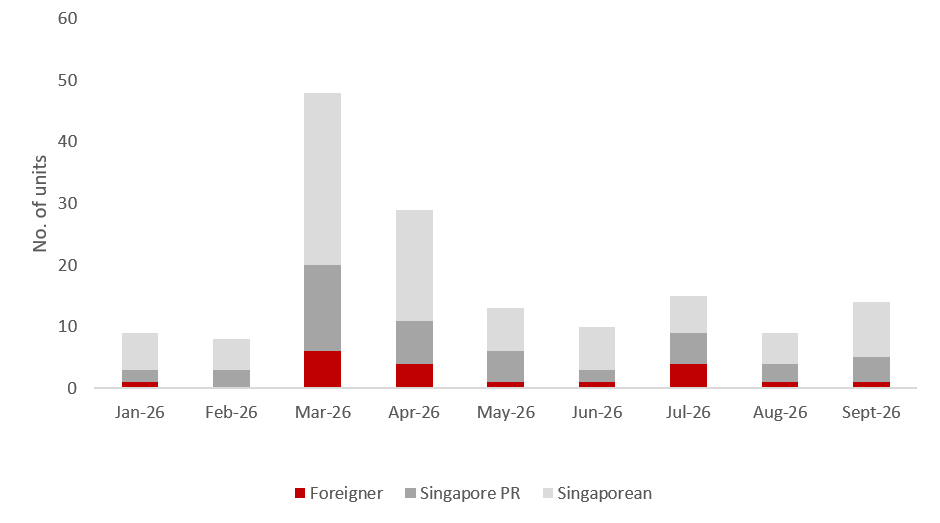
Non-landed luxury home transactions (excluding ECs) worth $5 million and above rose to 14 deals in September, up from nine in August. Singaporeans and Permanent Resident (PR) buyers accounted for 13 of these deals, of which nine were made by Singaporeans and four by PR buyers. The remaining luxury deal within the non-landed segment was made by a foreigner involving a four-bedroom unit (2,056 sq ft) at Upperhouse At Orchard Boulevard.
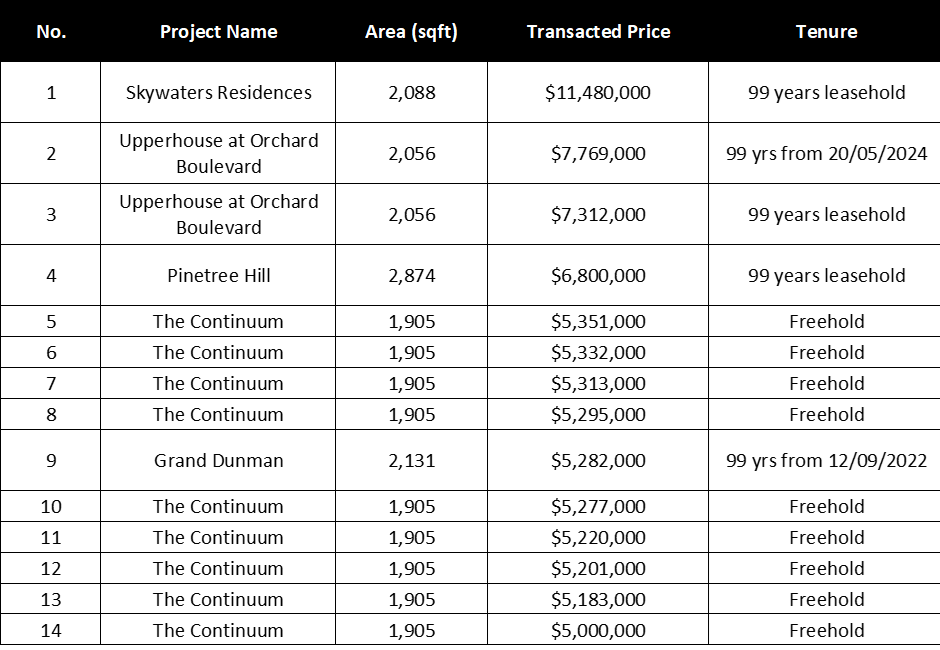
Within the non-landed private home segment, the priciest transaction took place at Skywaters Residences, where a 2,088 sq ft unit sold for $11,480,000 ($5,498 psf) to a Singaporean. It was also the priciest deal across the private residential segment for the month.
Table 3: Top luxury non-landed private home (excluding ECs) transactions for September 2026
Closing Thoughts and Forecast
Based on advance estimates released by the Ministry of Trade and Industry (MTI), Singapore’s economy continued to grow in 3Q 2026, albeit at a more measured pace of 5.4% year on year. Housing demand remains supported by healthy household balance sheets and a growing population, even amid headwinds such as softer employment conditions, and inflation driven by higher energy costs.
Transaction volumes are likely to be capped by a leaner launch pipeline, with an estimated 2,229 private residential units across five projects expected in 2H 2026. This may constrain full-year private home sales, despite still-healthy buyer sentiment.
Sales momentum could, however, pick up in the months ahead with major launches such as the 1,268-unit Thomson Reserve in Bishan and the 570-unit Lucerne Grand at Lakeside. As it stands, October could see stronger developer sales, with Lucerne Grand moving approximately 347 units, or 61% of its 570-unit stock during its launch weekend.
Against this backdrop, ERA Singapore expects new private home sales (excluding ECs) to reach around 9,000 units by year-end, barring any unforeseen circumstances.